
 |
|
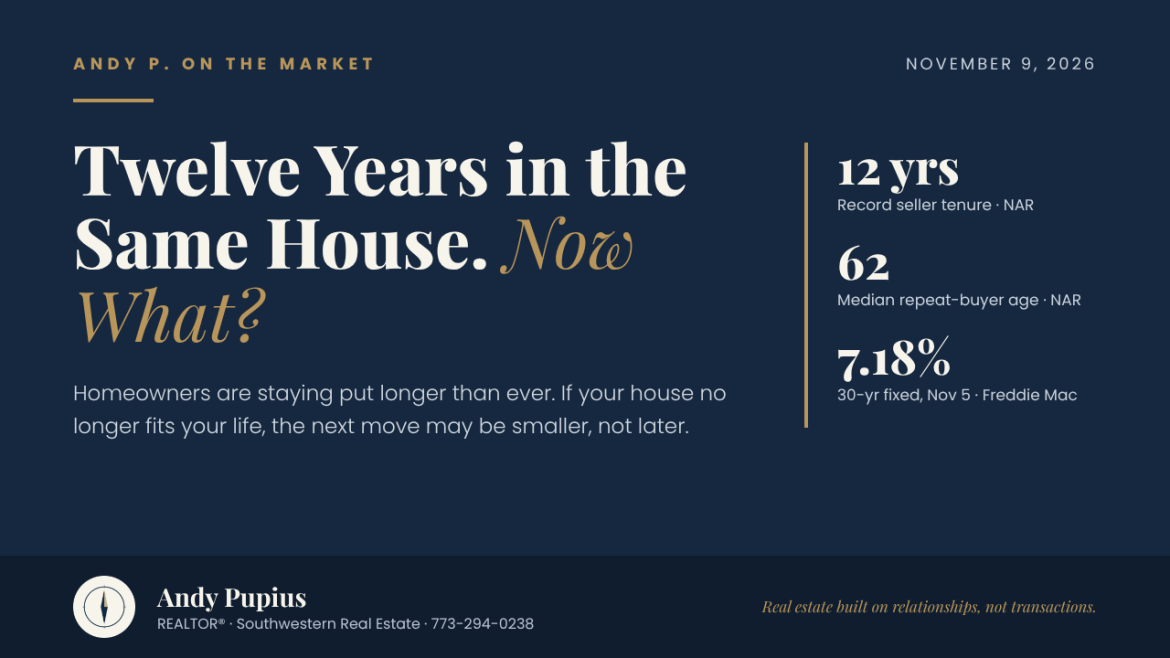
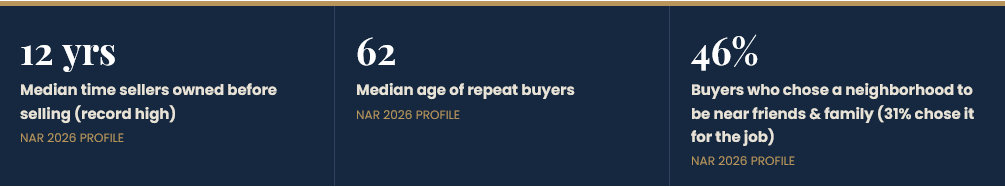
Homeowners are staying put longer than ever. If your house no longer fits your life, the next move may be smaller, not later. Here’s how I’d think it through. I hear some version of this sentence almost every week: “We’d love something smaller, but we’d never give up our rate.” The kids are grown, the stairs feel steeper, the yard eats the whole Saturday, and the house stays exactly where it is. Last week NAR released its 2026 Profile of Home Buyers and Sellers, and it puts hard numbers on that conversation. Sellers had owned their homes a median of 12 years before selling, the longest NAR has ever recorded. The typical repeat buyer is now 62, up from 36 in 1981. And the most common reason people sold was to move closer to friends and family. |
 |
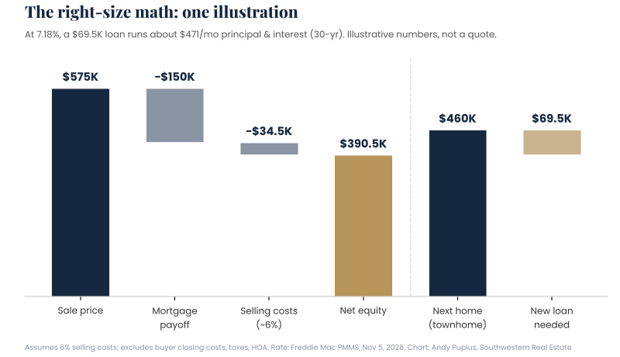
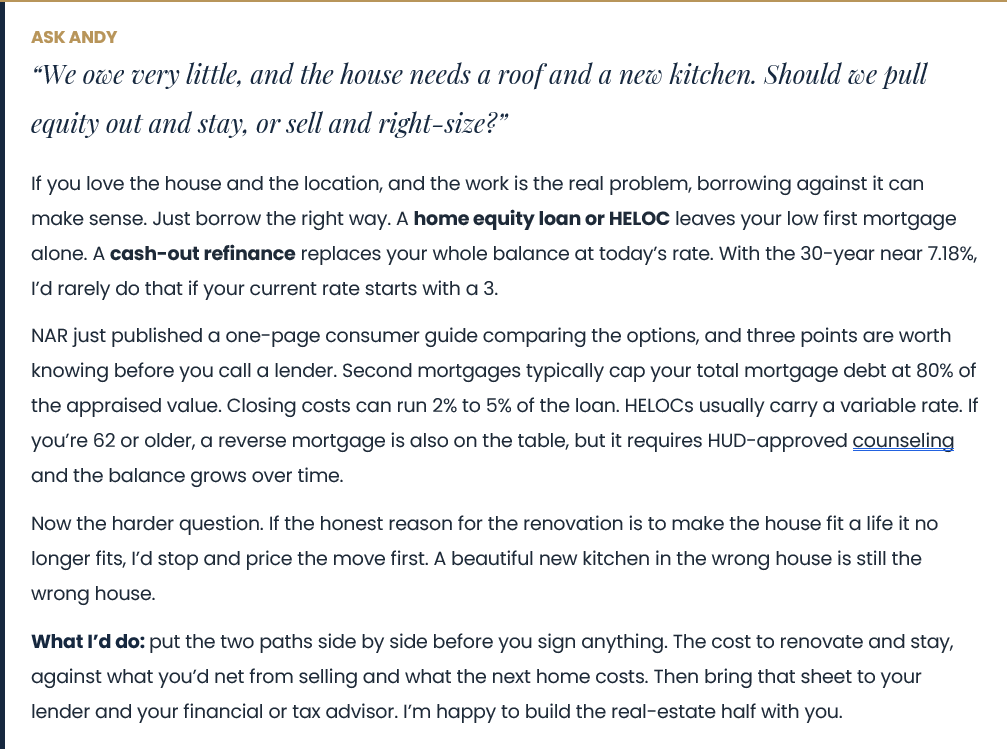
THE HEADLINE "Homeowners are trapped by their low rates." There’s truth in it. NAR itself says the lock-in effect of low-rate mortgages is likely a big reason people are staying longer. And with the 30-year fixed averaging 7.18% this week (Freddie Mac, Nov. 5), trading a 3% loan for a 7% one is a bad deal on paper. Rates have eased three weeks in a row, but they’re still close to a full point above where they were a year ago (6.22%). But that headline is written for the buyer who needs a big new mortgage. It misses the person who’s owned for a decade or more. For that owner, the rate is only half of the math. The other half is equity. WHAT THE NUMBERS ACTUALLY SAY You’re not swapping your rate. You’re shrinking your loan.
Here’s one illustration. The numbers are round on purpose; yours will differ.
|
 |
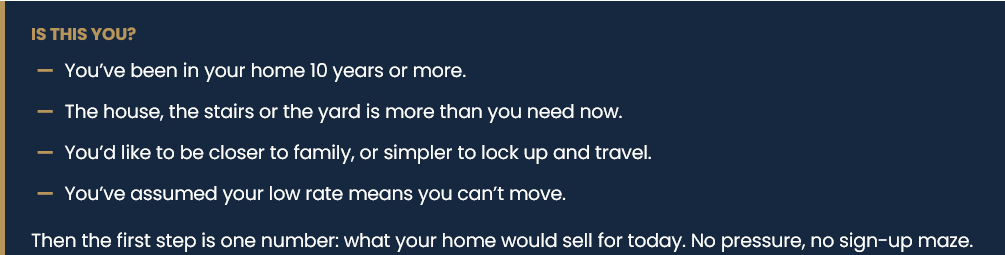
Start with the life, then run the numbers 1. Write down the next five years. Grandkids across town? A knee that’s done with stairs? Winters somewhere warm? The house should serve that plan, not the other way around. 2. Get your two real numbers. What your home would likely sell for today, and what you owe. The gap between them is your actual buying power. Most long-time owners are surprised by it. 3. Price the “after” home first. Tour a few townhomes or ranches before you ever list. It turns a vague idea into a monthly number you can compare. 4. Plan the order of the move. Sell first, buy first, or line them up together. Last week’s Ask Andy walked through that choice, and it matters more than the rate. My honest take: if the house no longer fits and the numbers show you can buy the next place with a small loan or none, I wouldn’t let a 3% rate keep you in the wrong house. If the house still fits, stay and enjoy it. Just make that a choice, not a default. |
 |
| NOW LIVE 1341 Chestnut Crossing, Lemont Speaking of right-sizing: as of Monday, November 9, my listing at 1341 Chestnut Crossing in Lemont is officially live on the MLS. It’s exactly the kind of home a lot of long-time owners tell me they’re looking for: room for the family when they visit, and a lot less house to keep up. 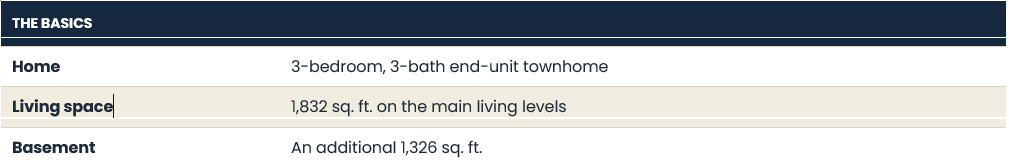 |
|
Around town, Nov. 9–15 — Wed., Nov. 11 — Veterans Day. Thank you to every veteran in our community. Today and every day. — Wed., Nov. 11 — Pages and Palettes, a family art show and children’s book fair with live music. 5:30–7 p.m., Ray Morrill Community Center, Wheaton. Free. — Thu., Nov. 12 — A City at War: Chicago. Kris Habermehl on how Chicagoland became a WWII production hub. 6–8 p.m., DuPage County Historical Museum, Wheaton. $50, food and cash bar. — Through Sat., Nov. 14 — last week for The Mother Road & Iconic DuPage Firsts exhibit at the DuPage County Historical Museum. — Sat., Nov. 14 — Smashing Pumpkins & Gourds. Bring your leftover pumpkins and smash them. 9:30–11:30 a.m., Rice Pool parking lot, Wheaton. — Coming up: Fri., Nov. 20 — Carol Stream Holiday Tree Lighting Extravaganza, 6–8 p.m., Ross Ferraro Town Center. Free. |
 |
|
Andy Pupius REALTOR® · Southwestern Real Estate · CFSP · RENE · PSA · AHWD 773-294-0238 · apupius@southwestern.com Real estate built on relationships, not transactions. Straight answers. Steady hands. Every detail handled. Sources: MRED / InfoSparks © 2026 ShowingTime (single-family, city-level, rolling 12 months through September 2026); Freddie Mac Primary Mortgage Market Survey, October 15, 2026. |